To reduce DSO, start with accurate invoices, confirmed payment terms, consistent follow-up and prompt dispute resolution. Reconcile cash receipts before contacting a customer, then review overdue balances and unresolved exceptions. Use automation where it removes a demonstrated delay; measure results against your own baseline rather than a vendor’s promised reduction.
Diagnose why customers pay late
Days sales outstanding (DSO) estimates the time it takes to collect receivables relative to credit sales. Use a consistent calculation and reporting period. Changes in sales, seasonality and customer terms can affect the result even when collection behavior is unchanged.
Separate invoices still within agreed terms from overdue balances. For overdue invoices, record the cause: missing purchase order, rejected delivery, disputed work, an unapplied payment, a missing approver or a customer cash constraint. Each cause needs a different response.
McKinsey’s working-capital guidance supports accurate billing and a separate process for disputed invoices. It does not establish a standard percentage improvement for Daylit or another vendor.
Six practical steps to reduce DSO
- Confirm terms before delivery. Record the agreed due date, billing contact, purchase-order requirements and approval process. Make those details available to sales, operations and finance.
- Send a complete invoice promptly. Match the price and quantity to the agreement, attach the required evidence and confirm receipt through the customer’s approved channel. Correct rejected invoices promptly.
- Use a consistent reminder process. Reference the invoice and due date, ask for a payment date and record the response. Tailor escalation to the account context. See automated payment reminders for service companies for workflow considerations.
- Apply received cash before chasing payment. Reconcile receipts, credits and partial payments so reminders reflect the balance actually due. Route uncertain matches to a reviewer.
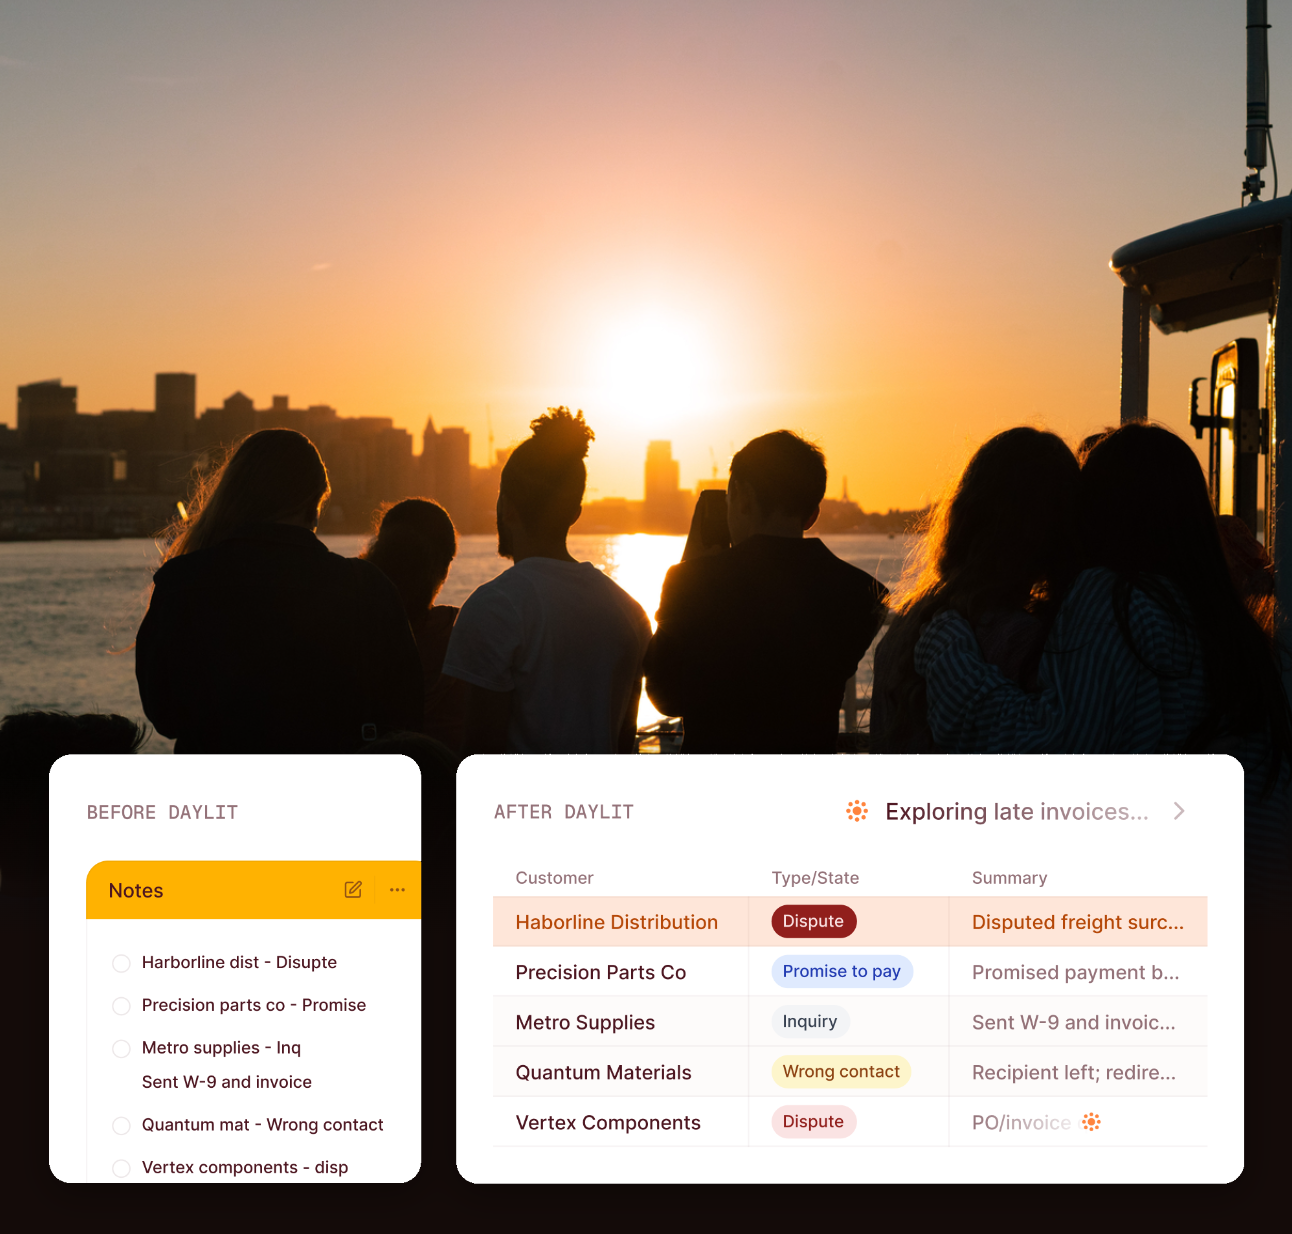
- Give disputes an owner. Capture the reason and supporting records, assign the responsible team and agree the next action. Avoid repeating standard reminders while a genuine dispute remains unresolved.
- Review the results together. Track DSO alongside overdue balances, days past terms, open disputes and unapplied cash. Investigate whether an improvement reflects faster collection, changed sales or financing.
Deloitte’s receivables guidance explains the importance of accurate billing records and timely cash application.

Put the DSO reduction plan into practice
Start with a representative set of invoices and a clearly defined bottleneck. Record the baseline, assign an owner and decide what evidence would show improvement. Choose an observation period that covers the relevant payment cycle; avoid judging the result from a few isolated payments.
| Problem | Action | Measure |
|---|---|---|
| Invoice rejected or not received | Verify billing requirements and delivery acknowledgment | Rejected invoices and elapsed time to acceptance |
| Follow-up missed | Use a reminder queue with a named owner | Overdue balance and commitments kept |
| Payment received but not matched | Reconcile remittances and route exceptions | Unapplied cash and time to correct posting |
| Dispute stalled | Assign a reason, owner and next action | Resolution time and amount legitimately recovered |
Use automation where it removes an observed delay
Before selecting software, demonstrate invoice delivery, a partial payment and a disputed invoice using representative data. Confirm the required ERP version, permissions, records and error-handling process. Request a written implementation plan rather than assuming a connector or deployment timeline.
Keep a human review path for uncertain matches, disputes and sensitive relationships. Compare pilot results with similar accounts and reporting periods, accounting for customer mix and sales changes. Expand the workflow after the team understands its exceptions.
Estimate cash impact without overstating ROI
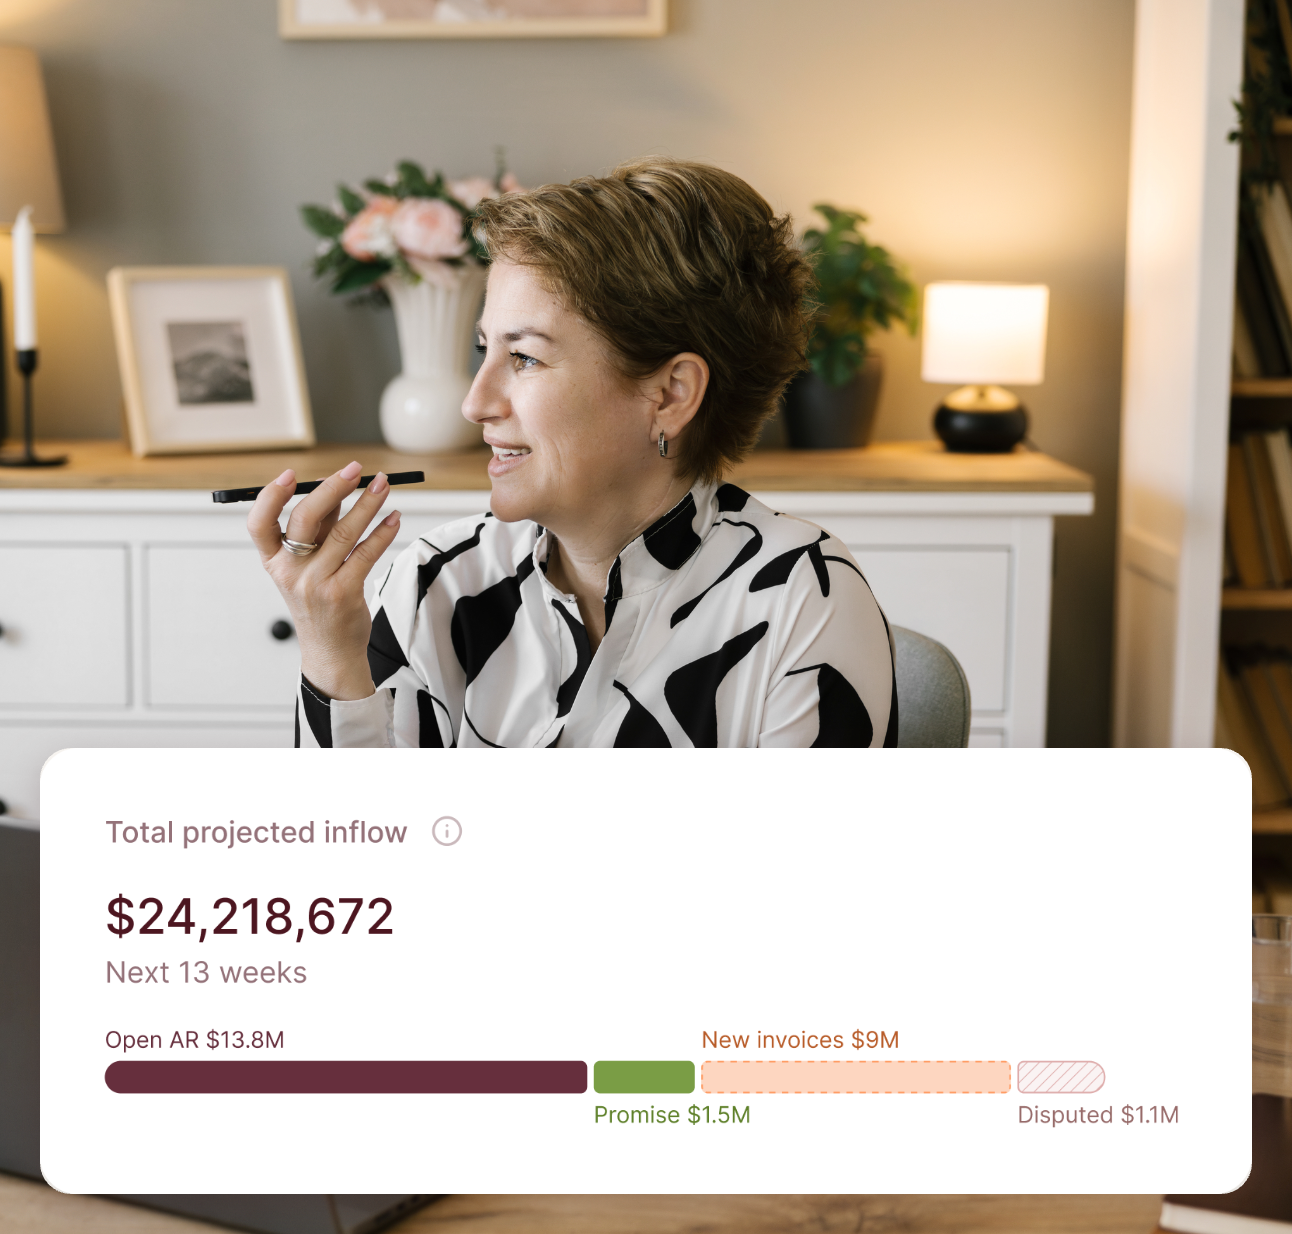
A simple sensitivity calculation is annual credit sales divided by 365, multiplied by the assumed DSO reduction. For a hypothetical $50 million in annual credit sales and a 15-day improvement, that is approximately $2.05 million in released receivables.
This is a one-time liquidity effect, not recurring annual profit or a promised software result. Separately estimate verified labor, processing and financing-cost savings, then subtract implementation and operating costs. See how to calculate accounts receivable automation ROI.

Separate faster collections from financing
A business can improve collections and still have a cash gap during agreed customer terms. Model supplier payments, inventory and payroll alongside expected receipts before choosing a financing option.
Factoring can provide cash against approved receivables, but it does not by itself make the customer pay sooner. Compare fees, recourse, reserves and collection responsibilities. CFO.com’s working-capital methodology discussion explains why receivables financing can affect reported DSO without improving underlying collection behavior. The linked historical methodology is not a current benchmark.
Frequently asked questions
What is a good DSO?
Use your own agreed terms and a relevant peer group. Match the period and calculation method, and distinguish invoices still within terms from overdue balances. A single cross-industry number can obscure the cause of delay.
Do payment reminders always reduce DSO?
No. Reminders can address missed follow-up, but a rejected invoice, unresolved dispute or customer cash constraint requires a different action. Check the reason for delay before increasing message frequency.
Should we offer an early-payment discount?
Compare the discount with the cost and value of receiving cash sooner. Use the actual number of days accelerated and consider whether the customer would otherwise have paid on time. Agree the discount in writing and account for it consistently.
How soon should we expect results?
Set milestones for invoice acceptance, follow-up, cash application and dispute resolution. Evaluate results over comparable payment cycles; there is no universal DSO reduction or payback period established by this article.
Does lower DSO mean more profit?
Not necessarily. Faster collection can release cash from receivables. Profit improves only where costs fall or attributable economic benefits exceed the costs of the changes.
Further reading
Accurate billing and separate dispute workflows support collections. See McKinsey’s analysis.
Related guidance: Automated Payment Reminders for Service Companies; Accounts Receivable Automation ROI: Costs and Value.
References
- McKinsey: Working capital process improvements. Read September 28, 2026.