Easterday Farms
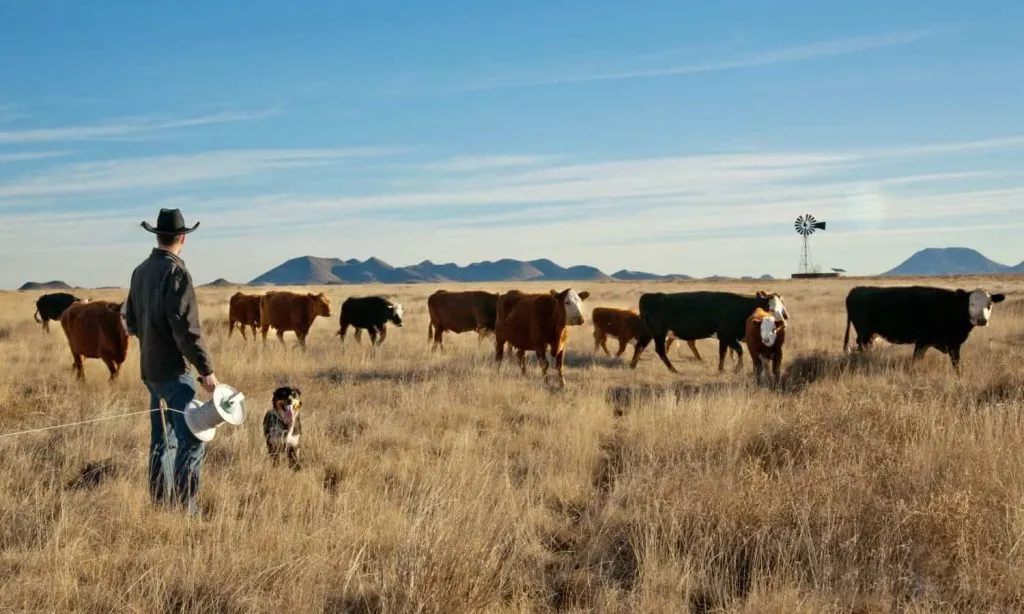
Ranchers and their enthusiasts are all too familiar with the tragic story of Easterday Farms. To our audience not yet acquainted with Gale Easterday, formula contracting, or the capitulation of the single family ranchers of America – inch a little closer.
The event which ended in unraveled fraud and a deadly car crash can be summarized, bluntly and apologetically, as an information and incentive mismatch. As entrepreneurs, we empathize with the outcome. As lenders, we recognize the need for change.
To say that big data could have helped avoid the event would be a bold claim. The reality is a more transparent, dynamic system can help ranchers fight back against formula contracting. Importantly, a better alternative to formula contracting can lead to happier ranchers, and thus, maybe even better burgers.
Allow us to explain how.
Too big to scale?
Feeding America, the NGO fighting Hunger, places emphasis on scale. Bigger producers and bulk orders means lower prices and better food access. As a result, the price of beef has steadily dropped over the past 20 years. Many ranchers, especially those producing under 50,000 pounds of livestock, are folding under the pricing pressure.
Cattle producers may combine sales contracts and financing arrangements to manage the interval between raising livestock and receiving payment. Pricing formulas, ownership and repayment obligations differ by contract.
A rancher should understand how the sales agreement interacts with financing and what happens if prices or cash receipts fall short of expectations.
The buyer is the lender
When the buyer also provides financing, review the pricing mechanism and potential conflicts of interest. A contractual incentive is not evidence that any named business manipulated market prices.
When a lender finances an operator against their inventory, they are betting on the business and its goods. In a good outcome, the business sells its inventory and pays off their debt. Alternatively, the business defaults and the lender liquidates the inventory into the free market.
Default provisions can affect the producer’s ability to sell livestock, refinance or continue operating. Compare those provisions with the alternatives before entering an agreement.
Review collateral rights, restrictions on alternative buyers and remedies after default with an adviser familiar with the proposed arrangement.
Market quotations alone do not explain a contract’s realized price. Examine quality adjustments, delivery obligations and the agreed calculation.
Create a new system
Though flawed, the formula contracting system is built on some solid ground. The ranchers need a cash advance on their future cattle sales. The lender needs protection for its risk. We believe the solution lies in introducing a third party.
When a third party lender can properly assess risk and contract in the free market, the operator wins. The business has more latitude to manage their cash flow without an imposing threat of a “margin call” (frankly, they have enough to worry about).
Business data can inform underwriting, but software does not guarantee fraud detection or accurate risk assessment. Lenders still need verification and appropriate controls.
Daylit’s We Heart Ranchers Program
Daylit’s view is that ranch-management records could help producers share a clearer picture of their business with lenders. Approval, terms and timing would still depend on the lender’s assessment.
To learn more about the Daylit We Heart Ranchers click here.
{{embedded-finance-learn-more}}
Further reading
Karen Mills describes how online lenders use business data in credit assessment. See Harvard Business School’s analysis.
Related guidance: SME Financing: Comparing Daylit and Bank Loans; Embedded Lending for SMB Software Platforms.
References
- Harvard Business School: Online Banks Fill Funding Needs for Small Business. Read September 28, 2026.